Banks hand Treasury record Sh205 billion in tax as compliance costs jump
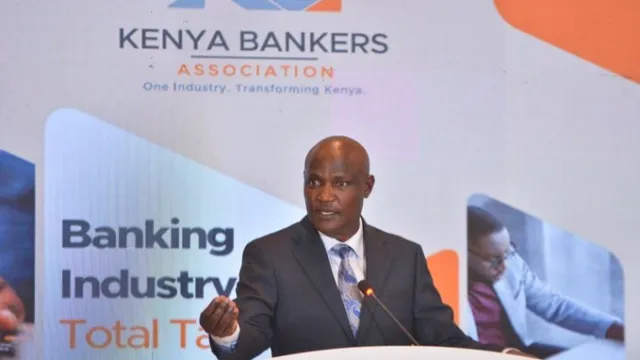
Treasury CS John Mbadi during the release of the 2025 Total Tax Contribution report prepared by PwC and the Kenya Bankers Association in Nairobi on Thursday.
Banks in Kenya delivered a record KES 205.58 billion in tax haul to the National Treasury in the year ended December 2025, a new report shows yet highlights that this feat came amid steep rise in operational costs for the industry.
According to the report by audit firm PwC in liaison with the Kenya Bankers Association, banks are now spending huge sums of money to meet tax compliance demands in an evolving environment.
Related
Bankers seek more time to meet tax compliance demands
Bankers push for loan pricing shake-up to spur borrowing
The 2025 Total Tax Contribution report notes that 33 participating lenders and microfinance institutions contributed roughly 8 percent of all the government receipts. Last year's contribution increased by 5.53 per cent from the amount recorded in 2024.
The taxes the lenders collected on behalf of the government hit KES 107.22 billion, being way higher than KES 98.36 billion, which is what the banks paid as a cost of doing business.
It is a trend that casts the lenders less as traditional corporate taxpayers and more as the Treasury's primary administrative engine for collections, a role that is increasingly mired in red tape and high costs.
The report lays bare the severe financial burden imposed by the tax environment in East Africa’s largest economy. During the year, average annual compliance cost per bank gre by 62.25 per cent, surging to nearly KES 31 million from KES 19.10 million reported in 2024.
While the cost of employing in-house tax experts came down, this was more than offset by the banks’ move to hire external support.
Facing a maze of regulations, banks more than doubled their costs on external tax consultants and legal advisers to an average of KES 20.2 million each, the study states.
Compliance costs
The average bank now dedicates the equivalent of three full-time employees to manage tax compliance matters, consuming on average 103 business hours every month and making 45 separate tax payments.
Lenders rated the overall complexity of the system at 3.19 out of 5, pointing the finger squarely at the five-day filing and payment cycle for withholding tax as a particularly onerous administrative nightmare.
The industry has long warned that frequent legislative changes, alongside implementation glitches with digital platforms such as iTax and eTIMS, are creating an environment of unpredictability.
While the Kenya Revenue Authority (KRA) credits these digital systems with driving revenue growth, banks reported that they frequently trigger reconciliation errors, forcing them to divert skilled staff away from revenue-generating functions and into routine compliance work.
Despite a healthy 17.63 per cent jump in pre-tax profits to KES 305.95 billion, the corporate tax borne by the banks increased by 2.06 per cent to KES 70.84 billion during the year under focus.
Withholding tax ccollected, which is a charge levied on payments the banks make to third parties, went up by 29.40 per cent to KES 43.95 billion.
This was driven by a 159 per cent increase in withholdings on royalties following an expanded legal definition, and a 292 per cent surge in withholdings on professional fees as banks invested heavily in digital systems.
Facing subdued private-sector borrowing and persistent credit risks, lenders in Kenya are increasingly seeking fresh income streams in government securities. The report shows that income from government paper expanded by 9.6 per cent, accounting for nearly 28 per cent of total income.
Crucially, a large portion of these bonds are tax-exempt, thereby dampening the banks' direct corporate tax obligations. Consequently, the sector's total tax rate, which is the proportion of pre-tax profits paid directly to the government, dipped to 32.15 per cent from 38.50 per cent previously.
In 2025, Pay-As-You-Earn (PAYE) collections decreased by 2.98 per cent, suggesting that bakers could be aggressively utilising tax reliefs, such as deductions for post-retirement medical funds and mortgage interest, to offset the impact of rising wages.
The growth in "people taxes" was instead carried by the full-year impact of new social levies, including the Affordable Housing Levy and the Social Health Insurance Fund.